Dozi
Dozi
HomeBlogs
Guides
Tools
Plans
LoginTry Dozi
DoziDozi

Your Home. Your Decision. India's homeowner-first platform for buying a flat or building a house, without the noise.

Product

  • Guides
  • Tools
  • Plans
  • Blogs

Company

  • About
  • Contact
  • Privacy Policy
  • Terms
support@dozi.ai
Bangalore, India

🇮🇳 Proudly built for India. All cost estimates and legal guidance are specific to Indian states, regulations, and market conditions.

© 2026 Dozi. All rights reserved.

Privacy PolicyTerms of ServiceRefund Policy
Free EMI calculator

Home Loan EMI Calculator

Find your monthly EMI, total interest and full amortization schedule. It starts at 8% as a planning figure, so change it to your bank’s rate.

  • No sign-up
  • Reducing balance method
  • Downloadable PDF

Calculate your EMI

Powered by Dozi
Monthly EMI
₹41,822
Total interest
₹50,37,281
Total amount
₹1,00,37,281

Principal 49.8 percent, interest 50.2 percent. Principal rupees 50,00,000, interest rupees 50,37,281.

Principal ₹50,00,000 (49.8%)
Interest ₹50,37,281 (50.2%)

Loan amount shown in rupees; use presets for lakhs/crores.

Amortization schedule▼
YearPrincipalInterestBalance
1₹1,05,683₹3,96,181₹48,94,317
2₹1,14,455₹3,87,409₹47,79,862
3₹1,23,955₹3,77,909₹46,55,907
4₹1,34,243₹3,67,621₹45,21,664
5₹1,45,385₹3,56,479₹43,76,279
6₹1,57,452₹3,44,412₹42,18,827
7₹1,70,520₹3,31,344₹40,48,307
8₹1,84,673₹3,17,191₹38,63,634
9₹2,00,001₹3,01,863₹36,63,633
10₹2,16,601₹2,85,263₹34,47,031
11₹2,34,579₹2,67,285₹32,12,453
12₹2,54,049₹2,47,815₹29,58,404
13₹2,75,135₹2,26,729₹26,83,269
14₹2,97,971₹2,03,893₹23,85,298
15₹3,22,702₹1,79,162₹20,62,596
16₹3,49,486₹1,52,378₹17,13,109
17₹3,78,494₹1,23,370₹13,34,616
18₹4,09,908₹91,956₹9,24,707
19₹4,43,931₹57,933₹4,80,777
20₹4,80,777₹21,087₹0

Monthly EMI by loan amount and tenure

At 8% a year, rounded to the nearest ₹100. Your bank's rate will differ, so use the calculator for your own figure.

Monthly home loan EMI at 8% by loan amount and tenure
Loan10 years15 years20 years25 years30 years
₹20 lakh₹24,300₹19,100₹16,700₹15,400₹14,700
₹30 lakh₹36,400₹28,700₹25,100₹23,200₹22,000
₹50 lakh₹60,700₹47,800₹41,800₹38,600₹36,700
₹75 lakh₹91,000₹71,700₹62,700₹57,900₹55,000
₹1 crore₹1,21,300₹95,600₹83,600₹77,200₹73,400
Inside Dozi

Ask it anything about your loan.

A calculator gives you the EMI. Dozi can talk through the decisions around it, using the details of your project, with no broker and no commission.

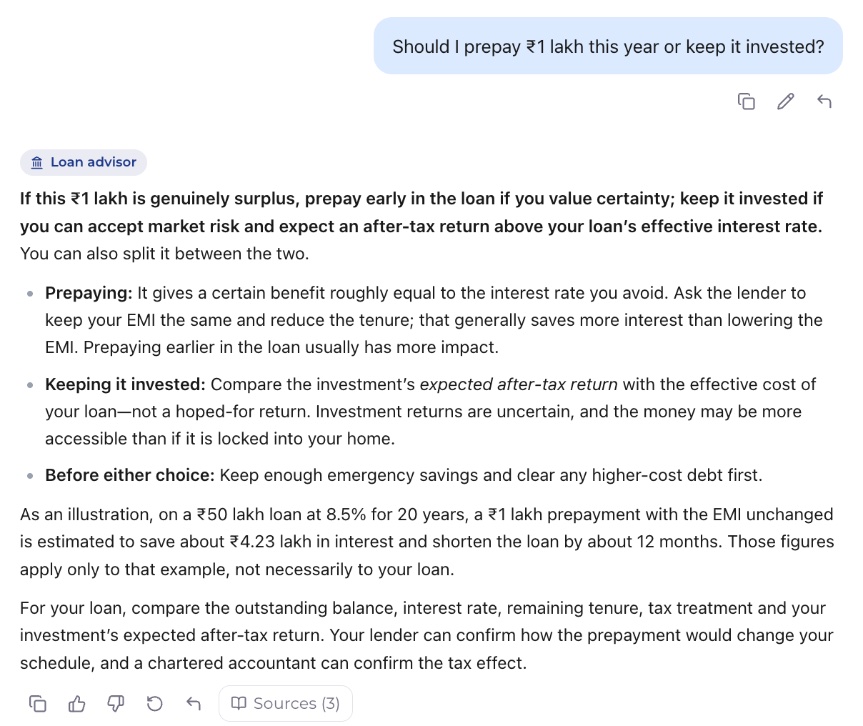
Dozi's chat answering: Should I prepay ₹1 lakh this year or keep it invested?

A real answer: “Should I prepay ₹1 lakh this year or keep it invested?”

If this ₹1 lakh is genuinely surplus, prepay early in the loan if you value certainty; keep it invested if you can accept market risk and expect an after-tax return above your loan’s effective interest rate. You can also split it between the two.

Prepaying: It gives a certain benefit roughly equal to the interest rate you avoid. Ask the lender to keep your EMI the same and reduce the tenure; that generally saves more interest than lowering the EMI. Prepaying earlier in the loan usually has more impact.

Keeping it invested: Compare the investment’s expected after-tax return with the effective cost of your loan—not a hoped-for return. Investment returns are uncertain, and the money may be more accessible than if it is locked into your home.

Before either choice: Keep enough emergency savings and clear any higher-cost debt first.

As an illustration, on a ₹50 lakh loan at 8.5% for 20 years, a ₹1 lakh prepayment with the EMI unchanged is estimated to save about ₹4.23 lakh in interest and shorten the loan by about 12 months. Those figures apply only to that example, not necessarily to your loan.

For your loan, compare the outstanding balance, interest rate, remaining tenure, tax treatment and your investment’s expected after-tax return. Your lender can confirm how the prepayment would change your schedule, and a chartered accountant can confirm the tax effect.

A real answer from Dozi's chat, for a test project in Bengaluru, 31 Oct 2026. Answers change with your project and over time.

Try asking

How monthly EMI is worked out

EMI = P × r × (1 + r)^n ÷ ((1 + r)^n − 1), where P is the loan, r is the monthly interest rate (the yearly rate ÷ 12 ÷ 100) and n is the number of months. Early EMIs are mostly interest, and more of each one goes to the loan as the balance falls. Our post on how home loan EMI is calculated explains it step by step.

Choosing a tenure

A longer tenure lowers the EMI but raises the total interest a lot. On ₹50 lakh at 8%:

EMI and total interest on a ₹50 lakh loan at 8%
TenureMonthly EMITotal interest
10 years₹60,664₹22,79,656
20 years₹41,822₹50,37,281
30 years₹36,688₹82,07,762

The rate decides this as much as the tenure. See home loan interest rates in India and fixed or floating rates.

How much EMI fits your income

Banks look at all your EMIs together as a share of your income, called FOIR, and many stay around 40% to 50%, though each sets its own limit. A bank's limit isn't the same as what feels comfortable, so check the EMI against your take-home pay and your other household costs.

The eligibility calculator works out how much a bank may lend on your income.

This is an estimate from the numbers you enter, using the reducing balance method. Your bank's sanction letter has the real figures, including fees and how the rate can change.

On this page

  • Frequently asked questions

Ask Dozi

Frequently asked questions

How to calculate home loan EMI per month?▼
Use EMI = P × r × (1 + r)^n ÷ ((1 + r)^n − 1), where P is the loan, r is the monthly rate (yearly rate ÷ 12 ÷ 100) and n is the number of months. This calculator does it for you and shows the total interest and full schedule.
How much monthly EMI for 50 lakh home loan?▼
About ₹41,800 a month over 20 years at 8%. Over 30 years it falls to about ₹36,700, but you pay much more interest in total.
What is the monthly EMI for a 30 lakh home loan?▼
About ₹25,100 a month over 20 years at 8%, and about ₹28,700 over 15 years.
How much is 20 lakh EMI per month?▼
About ₹16,700 a month over 20 years at 8%, and about ₹24,300 over 10 years.
What is the 40% EMI rule?▼
It is a common guideline that all your EMIs together should stay around 40% of your monthly income. It is not a law. Banks set their own limits, often 40% to 50%, and a lower share leaves more room for other costs.

Related calculators

Home Loan Eligibility Calculator

How much a bank may lend you on your income.

Open calculator

Stamp Duty & Registration Calculator

What you pay to register the property, on top of its price.

Open calculator

Rental Yield & ROI Calculator

What a property really returns once costs are counted.

Open calculator

Free guides on this

  • Home Loan Basics
  • Save Lakhs on Loan
  • Interest Rate Traps
  • Home Loan & Builder Payment Plans